

Starting a business can offer greater financial independence, flexibility and an opportunity to build something of your own. However, leaving a salaried job to become an entrepreneur is a major financial decision that requires careful preparation. Without a reliable plan, the pressure of paying rent, meeting household expenses and keeping a new business running can quickly become overwhelming.
For many aspiring entrepreneurs in Kenya, the biggest challenge is not necessarily finding a business idea. It is managing the financial transition from receiving a predictable monthly salary to depending on a business whose income may be irregular, especially during the first few months.
Before handing in your resignation letter, it is important to understand how much money you need to survive, how much capital the business requires and how long you can operate without earning a profit.
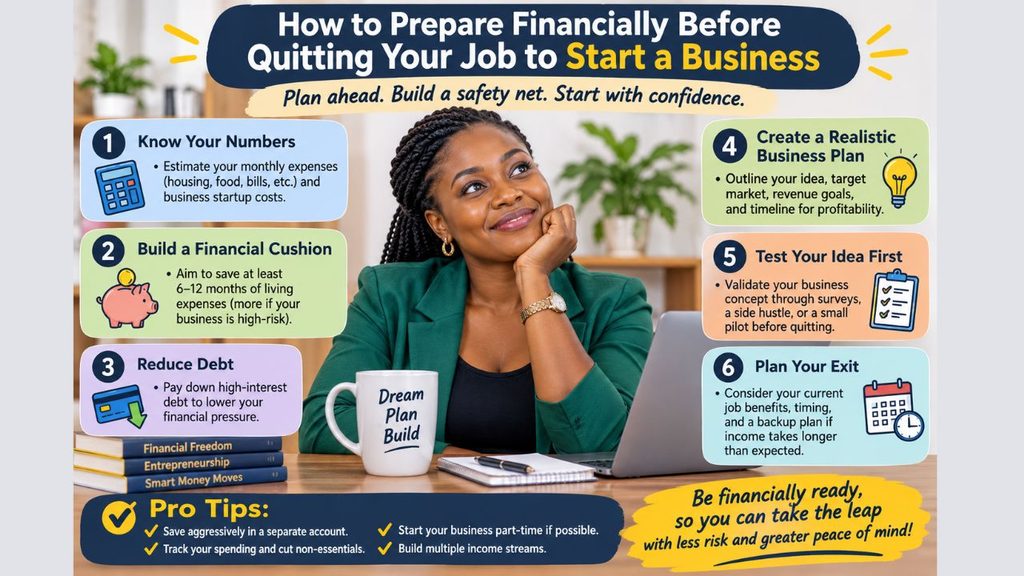
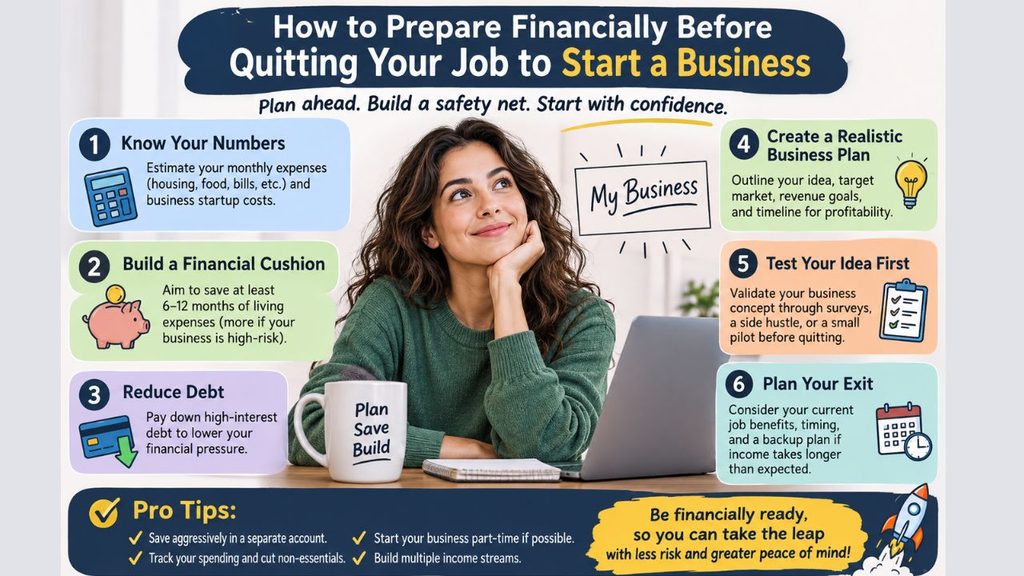
Financial preparation can help reduce unnecessary pressure and give your business enough time to grow. Here is how to prepare financially before quitting your job to start a business.
1. Calculate Your Monthly Personal Expenses
The first step is understanding how much money you need every month to maintain your current lifestyle. Many people underestimate their expenses when planning to leave employment, focusing mainly on rent and food while overlooking smaller costs that accumulate over time.
Prepare a realistic monthly budget covering essential expenses such as:
- Rent and household bills
- Food and groceries
- Transport and fuel
- Electricity, water and internet
- School fees and childcare
- Loan repayments
- Medical expenses
- Family responsibilities
- Personal and emergency expenses
Review your bank statements and mobile money transactions from the previous three to six months to understand your actual spending habits.
For example, if your essential monthly expenses amount to KSh30,000, you should not assume that your business will immediately generate enough money to cover that amount. You need savings to support yourself while the business develops.
A clear personal budget will help you determine how much money to set aside before leaving your job.
2. Build an Emergency Fund Before Resigning
One of the biggest financial mistakes aspiring entrepreneurs make is using all their savings to establish a business. Although investing in a new venture requires capital, you should avoid putting your entire financial safety net at risk.
An emergency fund is money reserved for unexpected expenses and personal survival. It should be kept separate from the money intended for business operations.
A practical target is to save at least three to six months of essential living expenses. If your income is uncertain, you have dependants or you are entering a business with a longer path to profitability, consider building a larger reserve.
For example, if your essential expenses are KSh30,000 per month:
- Three months of savings: KSh90,000
- Six months of savings: KSh180,000
- Nine months of savings: KSh270,000
These figures are illustrative and should be adjusted to your circumstances.
The purpose of this money is to ensure that you can continue paying essential bills even when the business has not started generating sufficient income.
3. Estimate the Actual Cost of Starting Your Business
Before resigning, calculate how much money you will need to establish and operate the business. Avoid relying on rough estimates or assumptions based on what other entrepreneurs have spent.
Different businesses have different financial requirements. An online business may need a computer, internet access, software and marketing, while a retail shop may require rent, stock, shelving, licences and transport.
Your startup budget should include:
Initial costs
- Business registration
- Equipment and tools
- Stock or raw materials
- Website development, where necessary
- Branding and marketing materials
- Furniture and other essential items
Monthly operating costs
- Rent and utilities
- Internet and telephone expenses
- Employee wages, if applicable
- Transport and delivery
- Stock replacement
- Marketing and advertising
- Professional services and other recurring costs
You should also include a contingency allowance for unexpected expenses. The amount will depend on the nature and risks of the business.
A detailed budget helps you avoid spending too much money on non-essential items before the business has established a reliable customer base.
4. Test Your Business Idea While You Are Still Employed
You do not necessarily have to resign before discovering whether customers are willing to pay for your products or services.
Where your employment contract and workplace policies allow it, consider testing the business on a small scale while still earning a salary. This can help you understand customer demand, pricing, competition and operating costs without immediately losing your regular income.
For example, someone planning to open a clothing shop could begin by selling selected products online. A person interested in catering could start with small orders for events and private customers. Someone planning to offer digital services could look for a few paying clients before investing in a full business setup.
The objective is to establish whether the idea has commercial potential.
Pay attention to actual sales rather than compliments from friends and family. People may say they like your business idea, but genuine demand is demonstrated when customers are willing to pay.
Testing the idea can also help you identify weaknesses and make adjustments before committing your savings.
5. Separate Your Personal Savings From Business Capital
Your personal money and business money should not be treated as one financial account.
Mixing the two can make it difficult to determine whether the business is profitable. It can also encourage unnecessary withdrawals that weaken the business’s ability to pay its expenses.
Create a separate account or maintain clearly documented financial records for business transactions. Record money received from customers, payments to suppliers, operating expenses and any money you introduce into the business.
You should also decide how much money you will take from the business for personal use. During the early stages, avoid withdrawing money simply because sales have been good in one week.
Remember that sales revenue is not the same as profit. A business may receive KSh100,000 in sales but spend most of that money on stock, rent, transport and other operating costs.
Good financial records will help you understand the real financial position of the business.
6. Pay Down Expensive Debt Before Leaving Employment
Existing debts can create additional pressure when you no longer receive a predictable salary.
Review all your outstanding loans, including bank loans, mobile loans, credit facilities and money borrowed from individuals. Identify the interest rates, repayment dates and outstanding balances.
Where possible, prioritise expensive debt and avoid taking unnecessary new loans to finance a business idea that has not yet been tested.
However, do not use all your emergency savings to clear debts if doing so would leave you without money for essential expenses. Balance debt repayment with the need to maintain a financial safety net.
If you have significant loan commitments, calculate whether the business can realistically support those repayments once you leave employment.
A business should not begin with financial obligations that it cannot reasonably meet.
7. Create a Financial Runway for the Business
A financial runway is the amount of time you can continue meeting your expenses before running out of available funds.
It is one of the most important calculations to make before quitting your job.
For example, suppose you have KSh300,000 set aside for business operations and the business is expected to spend KSh30,000 per month before generating enough revenue to cover its costs.
Your estimated runway would be:
KSh300,000 ÷ KSh30,000 = 10 months.
This is a simplified example. Actual calculations should account for changing expenses, unexpected costs, income received and the amount of working capital needed to keep the business operating.
Your personal emergency fund should be calculated separately. Do not count the same savings as both household protection and business capital.
Having a realistic runway gives you time to attract customers, improve your products and establish a stable revenue stream without immediately depending on the business to pay all your bills.
8. Keep Your Lifestyle Affordable During the Transition
Leaving employment does not mean you should immediately upgrade your lifestyle or spend heavily on appearances.
A new business may take time to generate consistent income. During this period, reducing unnecessary expenses can make a significant difference.
Consider postponing major purchases, reducing entertainment expenses, limiting unnecessary subscriptions and avoiding new financial commitments.
If you currently have expensive personal expenses, look for reasonable ways to reduce them before resigning.
You should also discuss the financial transition with your household, particularly if other people depend on your income. Agreeing on a realistic budget can prevent misunderstandings when the business begins operating.
The aim is not to live without comfort. It is to give yourself enough financial flexibility to manage the uncertain early stages of entrepreneurship.
9. Understand Business Registration, Taxes and County Permits
Financial preparation also means understanding the legal and regulatory costs of operating a business in Kenya.
Business registration is handled through the Business Registration Service, with applications available through the government’s eCitizen platform. Depending on the nature and structure of the venture, an entrepreneur may register a business name, partnership or company.
You should also establish which county permits and sector-specific licences apply to your activities. Permit requirements and charges can vary depending on the county and type of business.
Tax obligations should be included in your financial plan from the beginning. The Kenya Revenue Authority provides guidance on taxpayer registration, filing obligations and electronic tax invoicing.
KRA states that persons carrying on business are required to onboard eTIMS and issue electronic tax invoices, subject to the applicable provisions and arrangements. Entrepreneurs should confirm the requirements that apply to their particular business.
Failing to budget for registration, licences, tax compliance and record-keeping can create unexpected expenses after operations begin.
Useful official resources include the Business Registration Service at https://brs.go.ke/ and the Kenya Revenue Authority at https://www.kra.go.ke/.
10. Avoid Depending on Loans to Fund Every Business Expense
Borrowing money can help a business expand, purchase equipment or manage a temporary cash-flow challenge. However, relying heavily on loans before establishing a reliable source of revenue can expose a new entrepreneur to serious financial pressure.
Before borrowing, establish exactly how the money will be used and how the loan will be repaid.
For example, borrowing to purchase equipment that directly supports confirmed customer orders may be different from taking a high-interest loan to rent an expensive office before securing clients.
Compare the cost of borrowing with the expected financial benefit. Consider the repayment schedule, interest and what would happen if sales are lower than expected.
Where possible, start with a manageable business model and reinvest profits as the venture grows.
Do not assume that future sales will automatically cover today’s borrowing.
11. Develop More Than One Source of Income
If possible, avoid moving directly from a full-time salary to complete dependence on a new business.
You may be able to maintain a part-time income through freelancing, consultancy, online services, contract work or another activity that does not conflict with your employment obligations.
For example, someone starting a digital marketing agency could initially serve a small number of clients while building the business. A person opening an online shop could continue with freelance work until sales become more predictable.
An additional source of income can help cover personal expenses and reduce the amount of money withdrawn from the business.
However, be realistic about your time and energy. Managing several income-generating activities can become difficult, particularly when the business requires daily attention.
12. Set Clear Financial Targets Before Handing in Your Resignation
Do not resign simply because you are tired of employment or excited about a business idea. Establish measurable financial conditions that should be met before making the move.
For example, you may decide to resign only after:
- Saving at least six months of essential personal expenses.
- Raising the full amount required for startup costs.
- Keeping business capital separate from emergency savings.
- Testing the product or service with paying customers.
- Understanding monthly operating expenses.
- Preparing a realistic cash-flow forecast.
- Reviewing outstanding debts and repayment obligations.
You could also set a target for the business to generate a certain level of consistent revenue before leaving your job.
There is no universal figure that applies to every entrepreneur. The right target depends on your household responsibilities, business model, available savings and risk tolerance.
The important thing is to make the decision using financial evidence rather than excitement or pressure.
A Practical Financial Example Before Quitting Your Job
Consider an employee who wants to leave a salaried position and open a small retail business.
The individual estimates that essential household expenses are KSh30,000 per month and wants to maintain six months of personal savings.
The proposed financial plan could look like this:
| Financial requirement | Estimated amount |
|---|---|
| Six months of personal expenses | KSh180,000 |
| Business startup capital | KSh150,000 |
| Initial operating reserve | KSh60,000 |
| Emergency contingency for business costs | KSh30,000 |
| Total target savings | KSh420,000 |
This is only an illustrative budget, not a recommended amount for every business. Actual costs will depend on the location, business model, stock requirements and household circumstances.
The example demonstrates why entrepreneurs should calculate personal and business finances separately. If the employee uses the entire KSh420,000 to establish the shop, they may have no money left to support their household while waiting for the business to grow.
Common Financial Mistakes to Avoid Before Starting a Business
Even a promising business can struggle when its owner makes poor financial decisions. Some common mistakes include:
Resigning without savings: Leaving a job without an emergency fund can force an entrepreneur to depend on early sales before the business is ready.
Underestimating startup costs: Many people calculate the cost of opening a business but forget recurring expenses such as rent, transport, utilities and stock replacement.
Using household money as business capital: Spending money reserved for rent, food or school fees can create unnecessary financial problems.
Borrowing without a repayment plan: High-interest debt can become difficult to manage when business revenue is unpredictable.
Assuming customers will come immediately: A new business needs marketing, trust and time to attract regular customers.
Ignoring tax and licensing requirements: Registration, permits and compliance costs should be part of the original budget.
Confusing sales with profit: Revenue does not show how much money remains after expenses.
Avoiding these mistakes can help protect both your personal finances and the business.
Final Thoughts
Quitting a job to start a business can be a rewarding decision, but it should not be made without financial preparation. A good business idea needs more than enthusiasm; it requires capital, proper budgeting, a clear understanding of customer demand and enough savings to survive the early stages.
Before resigning, calculate your monthly expenses, build an emergency fund, estimate startup costs, reduce expensive debt and test your idea while you still have a regular income.
Most importantly, keep personal savings separate from business capital and establish a realistic financial runway.
You do not have to wait until you are wealthy to become an entrepreneur. However, you should understand the financial risks and prepare for the possibility that the business may take longer than expected to become profitable.
A carefully planned transition can give you a stronger foundation, reduce pressure and improve your chances of building a sustainable business.
Also Read: Russia Closes All Four Moscow Airports After Drone Attacks as Putin Hosts Ruto and African Leaders